A warehouse bought for £400,000 in 2015 can sit on the books at £300,000 while an estate agent values it at £650,000 — and both figures are correct. This article unpacks the difference between historical cost and fair value accounting, why UK SME balance sheets rarely reflect true market worth, and the specific moments — selling up, borrowing, insuring — when you need a real valuation instead.
When the trial balance will not balance, a suspense account keeps the books moving — but only if it is cleared quickly. This guide explains what suspense accounts are, why mystery balances appear, and walks through two real worked examples showing exactly how to trace and resolve them before they distort your reports or raise flags with HMRC.
A profitable month on paper and an empty-feeling bank account are not a contradiction — they are two different accounting lenses on the same business. This article unpacks the gap between accrual and cash basis accounting with a worked example, journal entries, and a step-by-step reconciliation so you can stop confusing timing differences with real trouble.
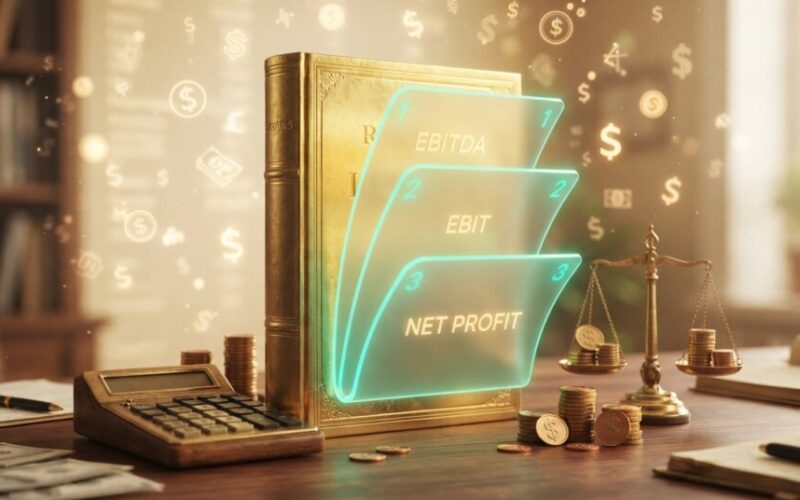
EBIT, EBITDA and net profit are not competing answers to the same question — they are three different lenses on the same set of numbers. This article unpacks what each metric strips out, why lenders and buyers favour different ones, and how a single SME's figures can swing from a £150,000 headline to a £60,345 bottom line depending on which line you stop at.
Debits and credits confuse most SME owners because bank statements use the terms backwards from how bookkeeping actually works. This article breaks down the one rule behind double-entry accounting, with worked examples showing stock purchases, supplier payments, and a running bank balance calculation.
Imagine you’re a financial professional, meticulously balancing the books for your company. You’ve got your revenue, expenses, assets, and liabilities all neatly…