Many SME owners and finance managers get tangled up the moment their business takes a minority stake in another company. Perhaps you have teamed up with another firm to build a joint venture, putting in £180,000 for a 30% share of a £600,000 business. The question that lands on your desk is simple but tricky: how do you show this in your own accounts? Do you treat it like a normal investment, consolidate it like a subsidiary, or something in between? Getting this wrong distorts your profit, confuses your balance sheet, and can trigger awkward questions from your auditor or bank. This article walks through exactly how to apply equity accounting under IAS 28, using real numbers from a £600,000 joint venture, so you can report your 30% stake correctly and explain it confidently to your board or lender.
What equity accounting actually means
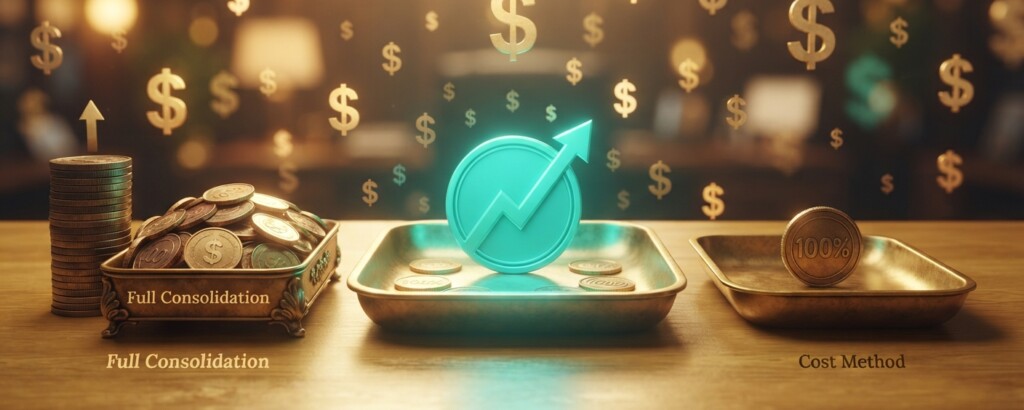
When your business owns enough of another company to control it — usually more than 50% — you consolidate it, meaning you add its full revenue, costs, assets and liabilities into your own group accounts, then strip out the portion owned by other shareholders. But when you hold an investment that gives you significant influence (for an associate, typically between 20% and 50%) or joint control (for a joint venture) rather than sole control, the rules change. This is where associates and joint ventures come in, and IAS 28 (or the equivalent sections in UK GAAP, FRS 102 Sections 14 and 15) sets out the approach: equity accounting.
Equity accounting is a halfway house. Instead of adding the joint venture’s full results into your accounts line by line, you show a single line on your balance sheet called ‘Investment in joint venture’, and you adjust that figure each year to reflect your share of the venture’s profits, losses and dividends. Think of it like a savings account that grows when the joint venture makes money and shrinks a little when it pays out cash to you. You are not reporting the joint venture’s turnover or costs in your own profit and loss account — only your share of its net result.
Why this matters for your business
If you are a finance manager preparing group accounts, misclassifying a joint venture stake as a subsidiary (full consolidation) will overstate your turnover and liabilities, which can mislead lenders assessing your covenants. Classify it as a simple cost-based investment instead of equity accounting it, and you under-report the value your 30% stake is actually generating, which understates your net assets and can make your balance sheet look weaker than it is. Getting the classification and the mechanics right protects the credibility of your numbers and keeps your statutory accounts compliant with the Companies Act 2006 and applicable accounting standards.
| Method | When it applies | What appears in your accounts |
|---|---|---|
| Full consolidation | You control the entity (usually over 50%) | 100% of revenue, costs, assets and liabilities, with a non-controlling interest line |
| Equity accounting (IAS 28 / FRS 102 s.14 & s.15) | Significant influence (associates, typically 20%-50%) or joint control (joint ventures) | One line for the investment, adjusted for your share of profit, loss and dividends |
| Cost method / fair value | Less than 20%, no significant influence | Investment held at cost or fair value, with dividends received shown as income |
Worked example: your £180,000 stake in a £600,000 joint venture
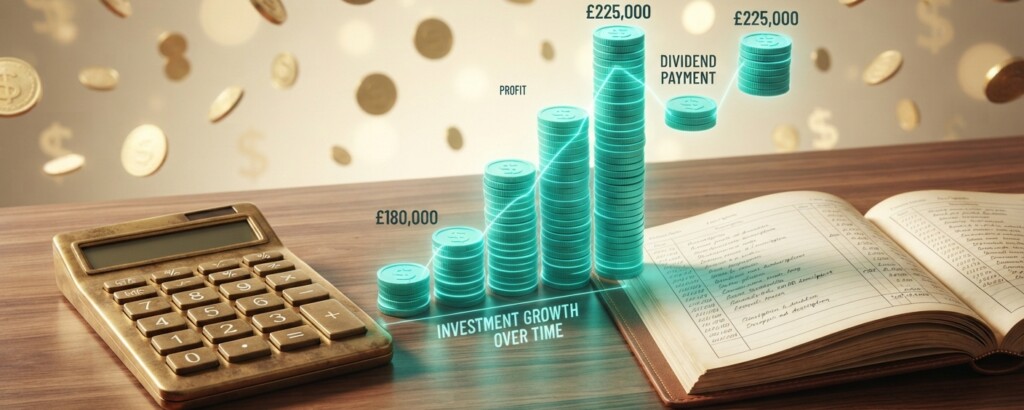
Let us put real numbers against this. Your company invests £180,000 in cash for a 30% stake in a joint venture valued at £600,000. You have joint control under the shareholders’ agreement, so this qualifies as a joint venture under IAS 28, and equity accounting applies. In its first year of trading, the joint venture makes a profit after tax of £200,000. It also declares and pays a dividend of £50,000 to its shareholders in proportion to their holdings.
| Initial investment (30% of £600,000) | £180,000 |
| Share of joint venture's profit (30% of £200,000) | £60,000 |
| Share of dividend received (30% of £50,000) | £15,000 |
| Carrying value of investment at year end | £225,000 |
Notice what is happening here. Your investment starts at £180,000, the cost of acquiring the stake. Over the year, your 30% share of the joint venture’s profit — £60,000 — increases the carrying value, because that profit has not yet been paid out to you and still belongs, in substance, to your share of the business. When the joint venture pays you £15,000 in dividends, that cash reduces the carrying value, because you are now receiving in cash what was previously just a paper increase in value. The net effect is a carrying value of £225,000 at year end, and your own profit and loss account shows £60,000 as ‘share of profit of joint venture’, not the dividend received.
| Account | Dr | Cr |
|---|---|---|
| Investment in joint venture | £180,000 | |
| Cash at bank | £180,000 |
Initial investment of £180,000 for a 30% stake in the joint venture
| Account | Dr | Cr |
|---|---|---|
| Investment in joint venture | £60,000 | |
| Share of profit of joint venture (P&L) | £60,000 |
Recognising 30% share of the joint venture's £200,000 profit for the year
| Account | Dr | Cr |
|---|---|---|
| Cash at bank | £15,000 | |
| Investment in joint venture | £15,000 |
Receipt of dividend representing 30% of the £50,000 distributed by the joint venture
The golden rule of equity accounting: your profit and loss account shows your share of the joint venture’s profit, not the cash dividend you receive. The dividend only ever reduces the carrying value on your balance sheet — it is never booked again as income, otherwise you would be counting the same profit twice.
This distinction trips up a lot of finance teams who are used to dealing with small shareholdings, where dividend income is simply booked as it is received. With equity accounting, the profit recognition happens when the joint venture earns the profit, not when it distributes cash. If the joint venture had made a loss instead of a profit, you would reduce the carrying value by your 30% share of that loss, and if cumulative losses ever exceeded your investment, you would generally stop recognising further losses once the carrying value reaches zero, unless you have a legal or constructive obligation to fund further losses.
Do not confuse significant influence or joint control with control. If your 30% stake comes with board representation, rights to participate in policy decisions, or access to technical information without joint control, you have significant influence (making it an associate); if decisions require unanimous consent, you have joint control (making it a joint venture). In either case, equity accounting applies in consolidated accounts. But if the agreement gives you a controlling vote or the ability to direct financial and operating policies unilaterally, you have control and must fully consolidate instead. Reviewing the shareholders’ agreement each year — not just at the point of investment — is essential, because governance arrangements can change.
Where this shows up in your financial statements
On your balance sheet, you will see a single line, typically under non-current assets, labelled ‘Investment in joint ventures’ or ‘Investment in associates’, showing the £225,000 carrying value in our example. On your profit and loss account, below operating profit, you will see a line for ‘share of profit of joint ventures’ showing £60,000. This keeps your core trading results — revenue, cost of sales, operating costs — clean and focused on your own business activities, while still giving readers of your accounts visibility of the value being generated through your joint venture relationship. For group reporting purposes, this also means your consolidated turnover figure is not inflated by a business you do not control, which matters if turnover is used to assess your company size thresholds under the Companies Act or covenant tests with lenders.
| Financial statement line | Where it appears | Amount in worked example |
|---|---|---|
| Investment in joint venture | Balance sheet, non-current assets | £225,000 |
| Share of profit of joint venture | Profit and loss account, below operating profit | £60,000 |
| Dividend received | Not shown separately as income | Reduces investment balance by £15,000 |
If you are preparing accounts under UK GAAP rather than full IFRS, FRS 102 Section 15 follows broadly the same mechanics in consolidated financial statements. Note that in individual (standalone) accounts under UK GAAP, equity accounting is not permitted and investments are held at cost less impairment or fair value; furthermore, companies applying FRS 105 (the micro-entities regime) cannot prepare consolidated accounts and must measure investments at cost less impairment. It is worth checking which reporting framework applies to your company before you build your group accounts, because the correct treatment genuinely differs depending on your size and the standard you report under.
Actionable takeaways
- Confirm whether your stake gives you significant influence (for an associate, typically 20%–50%) or joint control (for a joint venture) rather than control, since this determines whether you equity account or fully consolidate.
- Track your investment in joint venture as a single running balance: start at cost, add your share of profit, deduct your share of losses and dividends received each period.
- Never record a dividend from a joint venture as income on your profit and loss account — it should only reduce the carrying value of your investment on the balance sheet.
- Revisit your shareholders’ agreement annually, not just at acquisition, because changes to voting rights or governance can shift you between cost accounting, equity accounting and full consolidation without you realising it.
Need help getting your group reporting right?
If you are structuring a joint venture, acquiring a minority stake, or simply want your consolidated accounts to reflect the true economics of your investments, our team can walk through the numbers with you and make sure your reporting stands up to scrutiny from auditors, lenders and HMRC alike.