You send your management accounts to your bank manager and they mention your ‘EBITDA’. Your accountant talks about ‘EBIT margin’. Your own profit and loss account, at the very bottom, shows a completely different number called ‘net profit’. Which one is right? The honest answer is that they all are — they are just answering different questions. If you have ever felt uneasy nodding along in a meeting because you were not sure which profit figure someone meant, this article is for you. Understanding the difference is not academic: it affects how outsiders judge your business, how much you might be offered if you sell it, and whether you are making decisions based on the full picture or only part of it.
Why ‘Profit’ Isn’t One Number
In everyday conversation, profit sounds like a single fact: money left over after costs. In accounting, it is more like a set of photographs taken from different angles of the same building. Each photograph strips away or includes certain costs to answer a specific question. EBIT and EBITDA are two of the most common photographs used by lenders, investors and buyers, while net profit is the final figure that ends up in your statutory accounts after tax has been deducted. None of them is more ‘true’ than the others — but using the wrong one for the wrong purpose can lead to bad decisions, from overpaying for a business to underestimating how much cash you actually need to survive.
What Each Metric Actually Measures
EBIT stands for Earnings Before Interest and Tax. It shows how profitable the core trading operations of your business are, before you factor in how the business is financed (interest on loans) or where it is registered for tax purposes. Two nearly identical businesses could have very different net profits simply because one has more debt or operates in a different tax jurisdiction — EBIT strips that out so you can compare the underlying trading performance more fairly.
EBITDA goes a step further: Earnings Before Interest, Tax, Depreciation and Amortisation. Depreciation spreads the cost of physical assets, such as machinery or vehicles, over their useful life, while amortisation does the same for intangible assets, such as software or acquired goodwill. Both are non-cash charges — no money actually leaves the bank when you record them. EBITDA is popular with lenders and buyers because it gives a rough approximation of the cash-generating power of the business before financing structure, tax and accounting policy choices around asset write-downs are applied.
Net profit — sometimes called profit for the year, or the ‘bottom line’ — is what remains after every cost has been deducted: cost of sales, overheads, depreciation, amortisation, interest and corporation tax. This is the figure that flows into retained earnings on your balance sheet and, indirectly, the figure that determines how much you can safely draw out of the business as dividends.
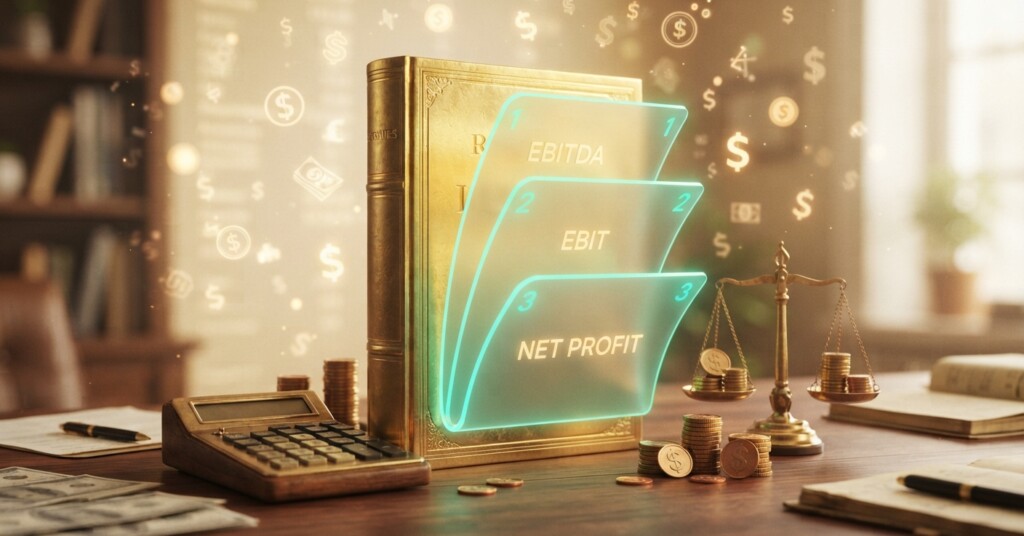
Think of it this way: EBITDA asks ‘how good is the trading engine?’, EBIT asks ‘how good is the trading engine after wear and tear on assets?’, and net profit asks ‘what’s actually left for the owners after everything, including the taxman?’
Worked Example: One Company, Three Profit Pictures
Let us take a fictional but realistic business, Riverside Joinery Ltd, a bespoke furniture maker turning over £850,000 a year. Below is a simplified version of its profit and loss account for the year, showing how each profit metric is built up step by step.
| Line item | Amount (£) |
|---|---|
| Revenue | 850,000 |
| Cost of sales | (480,000) |
| Gross profit | 370,000 |
| Operating expenses (excluding depreciation and amortisation) | (220,000) |
| EBITDA | 150,000 |
| Depreciation | (45,000) |
| Amortisation | (10,000) |
| EBIT | 95,000 |
| Interest expense | (18,000) |
| Profit before tax | 77,000 |
| Corporation tax (with marginal relief) | (16,655) |
| Net profit for the year | 60,345 |
Notice how the story changes depending on which line you stop at. If a bank is assessing whether Riverside Joinery can service a loan, it might focus on EBITDA of £150,000, because depreciation and amortisation do not use cash and interest is exactly what the loan repayment relates to. If a potential buyer is comparing Riverside against a rival with older, fully depreciated machinery, they might prefer EBIT, because it still reflects the real cost of maintaining and replacing equipment over time. And if you, as the owner, want to know what you can realistically pay yourself in dividends without eroding the company’s reserves, net profit of £60,345 is the number that matters.
| Revenue | 850,000 |
| Less: cost of sales | (480,000) |
| Gross profit | 370,000 |
| Less: operating expenses | (220,000) |
| EBITDA | 150,000 |
| Less: depreciation and amortisation | (55,000) |
| EBIT | 95,000 |
| Less: interest expense | (18,000) |
| Profit before tax | 77,000 |
| Less: corporation tax (with marginal relief) | (16,655) |
| Net profit for the year | 60,345 |
To see why depreciation matters so much to this calculation, it helps to look at the underlying journal entry that creates the £45,000 charge in the first place. Depreciation is not a cash payment; it is an accounting adjustment that recognises the wearing out of assets such as workshop machinery over their useful life.
| Account | Dr | Cr |
|---|---|---|
| Depreciation expense (P&L) | 45,000 | |
| Accumulated depreciation (Balance sheet) | 45,000 |
Annual depreciation charge on workshop machinery and vehicles, calculated on a straight-line basis over their useful economic life. No cash leaves the business when this entry is posted, which is exactly why EBITDA adds it back.
This is the crux of the difference between EBITDA and EBIT: the £45,000 depreciation charge, and the £10,000 amortisation charge alongside it, reduce the profit figure on paper but do not reduce your bank balance in that same period. Strip them out and you get EBITDA; leave them in and you get EBIT. Neither is wrong — they simply answer different questions about cash versus accounting profit.
Why This Matters When Talking to Banks, Buyers and Investors
If you are applying for finance, many lenders will ask for your EBITDA because it feeds into affordability calculations such as the debt service coverage ratio, which compares cash generated against loan repayments due. If you are selling your business, buyers frequently value SMEs as a multiple of EBITDA — for example, four or five times EBITDA is common in many trade sectors. Using the Riverside Joinery figures, an EBITDA of £150,000 at a multiple of five would suggest a headline valuation of £750,000, quite different from a valuation based on net profit of £60,345, which at the same multiple would suggest only £301,725. Knowing which metric a valuation is based on can make a six-figure difference to a negotiation.
Be cautious of relying on EBITDA alone. It ignores real costs your business will eventually have to pay in cash — replacing worn-out machinery, refinancing loans, or settling tax liabilities. A business with high EBITDA but heavy capital spending needs and large debts can still run into serious cash flow trouble. Always look at EBITDA alongside net profit and, ideally, actual cash flow from operations before drawing conclusions about financial health.
Which Metric Should You Use, and When
- Use EBITDA when comparing the underlying trading performance of businesses with different financing structures, tax positions or asset ages — useful for benchmarking against competitors or presenting to prospective buyers.
- Use EBIT when you want a fairer comparison that still accounts for the real cost of using and replacing equipment, particularly in capital-intensive sectors such as manufacturing, construction or haulage.
- Use net profit when deciding what can safely be paid out as dividends or disclosed in your statutory accounts filed at Companies House (taxable profit, calculated by adjusting profit before tax, is what is reported to HMRC for corporation tax purposes).
- Use all three together when preparing board packs or lender submissions, so readers can see both the underlying trading strength and the final outcome after financing and tax.
Takeaways You Can Apply This Week
- When someone quotes you a profit figure, always ask which line of the profit and loss account it refers to — EBITDA, EBIT and net profit can differ by tens of thousands of pounds even in a modest SME.
- Before agreeing a valuation multiple with a buyer or investor, confirm exactly which metric the multiple is applied to, since the same multiple applied to EBITDA versus net profit can produce wildly different headline values.
- Do not treat EBITDA as a proxy for cash in the bank — always cross-check it against your actual cash flow statement and upcoming capital expenditure needs before making borrowing or investment decisions.
- When preparing management accounts for your board or lender, present EBITDA, EBIT and net profit on the same page so everyone is working from a shared, transparent picture rather than one selectively chosen number.
Still unsure which profit metric matters most for your business?
Our team helps SME owners and finance managers translate confusing financial reports into clear, decision-ready information — from EBITDA calculations to full statutory accounts preparation.