If you are an SME owner who has ever asked your finance manager why the business shows a profit in the accounts but the bank balance tells a different story, revenue recognition is very likely part of the answer. Many owner-managed businesses raise an invoice, get paid, and assume the money should hit the profit and loss account there and then. Under UK accounting rules, that is often wrong, and getting it wrong can distort your management accounts, mislead lenders, and even trigger awkward questions from an auditor or accountant. This article walks through the five-step revenue recognition model used in IFRS 15 and FRS 102, with a full worked example using real numbers, so you can see exactly how and when revenue should hit your accounts.
Why revenue timing is a real business problem
Most SMEs eventually sign contracts that bundle more than one thing together: a product plus installation, a licence plus a year of support, or a project fee plus ongoing maintenance. If you invoice the whole contract value upfront and book it all as revenue immediately, your profit for that month looks excellent, but the following eleven months look artificially weak, because you have already spent the revenue on paper. This matters far beyond presentation. Lenders assess covenants using your reported profit. Bonus schemes and management targets are often based on monthly or quarterly revenue. Corporation tax computations start from accounting profit. If revenue is recognised in the wrong period, all of these decisions are being made on the wrong numbers, and the mismatch usually surfaces at the worst possible time, such as during due diligence for a sale or a bank review.
What the five-step model actually says
Both IFRS 15, used by companies applying UK-adopted IFRS or FRS 101, and FRS 102, the standard most UK private companies use, share the same underlying logic for how revenue should be recognised. Strip away the technical language and the model is really just a disciplined way of answering one question: when has the customer actually received the value you promised them? The standard breaks that question into five practical steps.
- Identify the contract with the customer: a real, agreed commitment meeting enforceable criteria, not just an informal quote or vague intention.
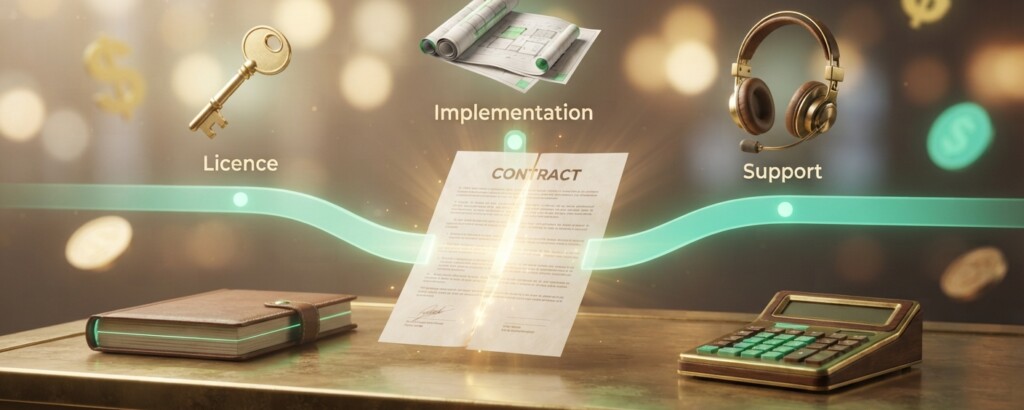
- Identify the separate performance obligations: the distinct promises within the contract, such as a software licence, an implementation project, and ongoing support.
- Determine the transaction price: the total amount you expect to be entitled to, after any discounts, rebates or variable elements.
- Allocate the transaction price to each performance obligation, usually based on what each element would sell for on its own, known as its standalone selling price.
- Recognise revenue as each obligation is satisfied, either at a single point in time, such as handing over a licence, or over time, such as a twelve month support contract.
Worked example: a £60,000 software and support contract
Say your business, a mid-sized software reseller, signs a contract with a customer worth £60,000, covering three elements: a perpetual software licence, a fixed-fee implementation project, and twelve months of technical support. The full £60,000 is invoiced and collected upfront on day one. Many business owners would be tempted to recognise all £60,000 as revenue the moment the invoice is raised. Under the five-step model, that would overstate profit this month and understate it for the rest of the year, because two of the three promises have not yet been delivered.
Step four requires the £60,000 to be split across the licence, the implementation and the support, based on what each element would cost if it were sold on its own. Those standalone selling prices come to £30,000 for the licence, £15,000 for implementation and £18,000 for support, a total of £63,000. The customer has effectively received a £3,000 bundle discount, and that discount is spread proportionally across all three elements rather than dumped entirely onto whichever item is delivered first.
| Performance obligation | Standalone selling price (£) | % of total SSP | Allocated transaction price (£) |
|---|---|---|---|
| Software licence | 30,000 | 47.6% | 28,571 |
| Implementation services | 15,000 | 23.8% | 14,286 |
| Support (12 months) | 18,000 | 28.6% | 17,143 |
| Total | 63,000 | 100% | 60,000 |
With the price allocated, step five asks when each promise is actually satisfied. The licence is handed over and accepted immediately, so it is recognised in full at that point in time. The implementation project runs over an agreed three months, so its allocated £14,286 is spread across those three months. The support contract runs for twelve months and is recognised evenly, £17,143 divided by twelve. Here is what revenue looks like in month one alone.
| Licence revenue recognised (delivered in full) | £28,571 |
| Implementation revenue recognised (1 of 3 months) | £4,762 |
| Support revenue recognised (1 of 12 months) | £1,429 |
| Total revenue recognised in month one | £34,762 |
| Remaining deferred revenue carried forward | £25,238 |
| Account | Dr | Cr |
|---|---|---|
| Bank | 60,000 | |
| Deferred revenue (contract liability) | 60,000 |
Cash received in full at contract signing; nothing is recognised as revenue yet because none of the promises have been delivered.
| Account | Dr | Cr |
|---|---|---|
| Deferred revenue (contract liability) | 34,762 | |
| Revenue: software licence | 28,571 | |
| Revenue: implementation services | 4,762 | |
| Revenue: support services | 1,429 |
Month one recognition once the licence has been delivered, one third of the implementation project is complete, and one month of support has been provided.
IFRS 15 vs FRS 102: what is different for SMEs
Historically, Section 23 of FRS 102 used a less prescriptive approach to revenue, based broadly on the transfer of risks and rewards and the stage of completion of a contract. However, following the Financial Reporting Council’s Periodic Review 2024, revised Section 23 aligns FRS 102 closely with IFRS 15, establishing the five-step model for accounting periods beginning on or after 1 January 2026. While FRS 102 retains several practical simplifications compared to full IFRS 15, the core five-step principles now apply directly under UK GAAP. If your business reports under FRS 102, ensuring your contracts, accounting systems, and finance processes reflect this five-step framework is essential for compliance under the updated standard.
The date you invoice a customer is a cash flow and VAT question. The date you recognise revenue is an accounting question. They are often not the same date, and confusing the two is one of the most common errors in SME management accounts.
Do not confuse revenue recognition for your management and statutory accounts with the VAT tax point on your sales invoice. You may correctly need to account for VAT on the full £60,000 at the point the invoice is raised, while only recognising £34,762 of accounting revenue in that same month. Keep these two calculations clearly separate, and make sure your bookkeeping software has a proper deferred revenue or contract liability account, otherwise your VAT return and your management accounts will tell two conflicting turnover stories to the same reader, which is a red flag to any lender, investor or auditor.
Common mistakes SMEs make
- Recognising the full value of an annual support contract as revenue on the invoice date, rather than spreading it evenly across the year it covers.
- Applying a bundled discount entirely to the first item delivered, instead of spreading it proportionally across every performance obligation.
- Failing to carry a deferred revenue balance on the balance sheet for amounts invoiced or collected before the related work has been done.
- Ignoring genuine evidence of progress, such as milestones or hours worked, on long implementation projects, which leads to lumpy and unrealistic profit swings from one month to the next.
Takeaways you can apply this week
- Map every customer contract that includes more than one deliverable against the five steps before deciding when any of it should be recognised as revenue.
- Build a simple allocation table, like the one used above, for each bundled contract using standalone selling prices, and keep it on file for your accountant or auditor.
- Set up a dedicated deferred revenue or contract liability code in your bookkeeping software so that cash received in advance is never mistaken for earned profit.
- If you report under FRS 102, ensure your systems, templates, and multi-element contracts comply with the five-step model that took effect for accounting periods beginning on or after 1 January 2026.
Want your revenue recognition checked before your next set of accounts?
Our team helps SME owners and finance managers apply IFRS 15 and FRS 102 correctly, with practical, jargon-light support and worked examples built around your own contracts.