A supplier is suing you for £40,000. A customer says your product caused damage and wants compensation. An ex-employee has lodged an unfair dismissal claim. None of these have been settled, so is there anything to put in the accounts? Many SME owners assume the answer is no — nothing has actually been paid, so why record it? But accounting standards see it differently, and getting this wrong can mean your accounts overstate profit, your bank is misled about your true financial position, or your auditor refuses to sign off. This article walks through exactly when a legal claim, warranty issue, or dispute must be booked as a provision, when it only needs a note in the accounts, and when you can safely ignore it — using real numbers throughout.
Provision or contingent liability — what is actually the difference?
A provision is a liability where you are not sure exactly when you will pay or exactly how much, but you are fairly confident you will have to pay something. Because you are confident, you record it in the accounts now, as an expense and a liability, even though no cash has moved yet. A contingent liability is different — it is a possible obligation that depends on something uncertain happening in the future, such as a court ruling against you. Because it is only possible, not probable, you do not record it as a liability. Instead you disclose it in a note to the accounts, explaining what it is and roughly how much it could cost if it goes against you. The distinction matters enormously: book too many claims as provisions and you understate profit and alarm your bank unnecessarily; fail to book a claim you should have provided for, and your accounts are misleading, your tax computation may be wrong, and your auditor will likely qualify the accounts.
The three-question test that decides everything
- Present obligation — has a past event already created a legal or constructive obligation? For example, an employee has been dismissed giving rise to a claim, faulty goods have already been sold, or you have already announced a restructuring to staff.
- Probable outflow — is it more likely than not, meaning over 50 per cent likely, that you will actually have to pay money or transfer some other economic benefit to settle it?
- Reliable estimate — can you put a reasonably confident figure on the amount, even if it is a best estimate rather than an exact number?
IAS 37 and FRS 102 use almost identical wording for this test, because FRS 102 Section 21 was deliberately written to mirror IAS 37. If the answer to all three questions is yes, you must book a provision. If the outflow is only possible rather than probable, or you cannot estimate it reliably, you disclose it as a contingent liability instead. If the chance of paying out is remote, you generally do not need to mention it at all.
Worked example: the unfair dismissal claim at Riverside Fabrications Ltd
Riverside Fabrications Ltd is a metal fabrication business with turnover of around £3.2 million. In February, a former production manager was dismissed and has now lodged an employment tribunal claim for unfair dismissal, seeking £40,000 in compensation. The finance manager needs to decide, at the year-end of 31 March, whether this needs a provision, a disclosure note, or nothing at all. The company’s employment solicitor has given a written assessment of the likely outcomes, which is exactly the kind of evidence auditors and lenders will expect to see.
| Test result | Probability of outflow | Accounting treatment | Typical example |
|---|---|---|---|
| Probable and reliably estimable | More likely than not (over 50 per cent) | Book as a provision on the balance sheet | A warranty claim you expect to lose, or a legal case your solicitor rates as likely to settle |
| Possible but not probable | Under 50 per cent, but not remote | Disclose as a contingent liability in the notes only | A case still at an early stage, or where the evidence is weak on both sides |
| Remote | Very unlikely to happen | No provision and normally no disclosure needed | A speculative threat of legal action with no formal claim lodged and no legal basis identified |
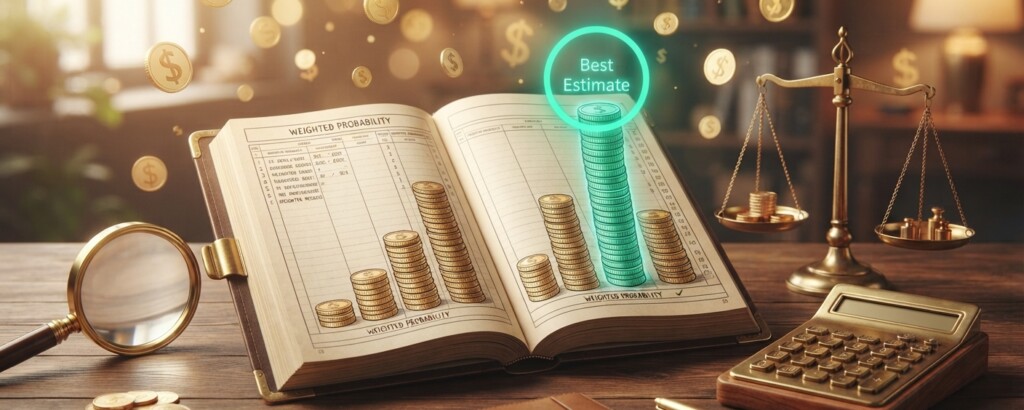
For Riverside, the solicitor’s letter puts the case firmly in the first category: a past obligating event occurred when the employee was dismissed in February, creating a present obligation if the dismissal was unfair, and the solicitor believes the company is more likely than not to lose in some form. That satisfies the first two questions. The remaining task is putting a reliable figure on the amount — and this is where many SME owners go wrong, either by booking the full £40,000 claimed, or by ignoring it because the final figure is not yet known. Neither approach reflects the standard’s requirement for a best estimate. Under IAS 37 and FRS 102, while the single most likely outcome (£25,000) is the standard starting point for an individual claim, other outcomes must be considered; because those other outcomes are mostly higher, weighting the realistic outcomes provides a defensible basis for an adjusted best estimate.
| 60 per cent chance of losing and settling at £25,000 | £15,000 |
| 30 per cent chance of losing the full claim of £40,000 | £12,000 |
| 10 per cent chance of successfully defending the claim | £0 |
| Best estimate provision required at 31 March | £27,000 |
This is a genuinely different figure from either the full £40,000 claim or a nervous guess. Under IAS 37 (paragraph 40) and FRS 102 (paragraph 21.7), for a single obligation the individual most likely outcome is generally the primary benchmark, with expected value formally specified for large populations of items. However, both standards require an entity to consider other possible outcomes: where the remaining outcomes are mostly higher (here, a 30 per cent chance of £40,000 versus only 10 per cent of zero), the best estimate must be higher than the £25,000 modal outcome. Weighting the scenarios achieves that required upward adjustment to £27,000, providing an objectively reasoned figure that an auditor can verify in the working papers.
| Account | Dr | Cr |
|---|---|---|
| Legal claims expense (profit and loss account) | £27,000 | |
| Provision for legal claims (balance sheet liability) | £27,000 |
Records Riverside Fabrications Ltd’s best estimate provision for the unfair dismissal claim at 31 March, based on the solicitor’s assessment of likely outcomes adjusted for higher potential payouts.
The most common mistake is not booking too little — it is failing to revisit the figure. Provisions must be reassessed at every reporting date, not set once and forgotten. If the tribunal hearing is pushed back, if new evidence emerges, or if the solicitor’s assessment changes, the provision needs updating, with the movement running back through profit and loss. A second frequent error is providing for the worst-case scenario out of caution rather than the genuine best estimate, which quietly understates reported profit and can distort management decisions such as dividend payments or lending covenant calculations.
IFRS versus FRS 102 — what actually differs for a UK SME
Most UK SMEs report under FRS 102 rather than full IFRS, and the good news is that Section 21 of FRS 102, covering provisions and contingencies, was written to closely follow IAS 37. The three-question test above applies under both frameworks in essentially the same way. An important practical consideration under both frameworks relates to discounting. Where the amount and timing of settlement are far in the future — for example, a long-running environmental remediation obligation expected to be settled in five years — both standards require the provision to be discounted to present value if the effect of the time value of money is material. For most SME legal claims and warranty provisions, which tend to resolve within twelve to eighteen months, the discounting effect is usually immaterial and can reasonably be ignored, but it should still be considered and documented rather than skipped by default. On the tax side, contrary to common misconception, HMRC does not automatically disallow all provisions until paid: under UK tax law (CTA 2009 s 46 and Herbert Smith v Honour), an accounting provision that accords with GAAP for allowable revenue expenditure is generally tax-deductible when recognized, provided it is estimated with sufficient accuracy and not barred by specific statutory timing rules. Where a provision does fail these criteria or relates to disallowable items, it is added back in the tax computation, creating a timing difference to track for deferred tax.
Actionable takeaways
- At every reporting date, run every open legal claim, warranty issue, or dispute through the three-question test — present obligation, probable outflow, reliable estimate — rather than relying on gut feel about how serious it looks.
- For a single legal claim, start with the most likely outcome and consider whether other outcomes are mostly higher or lower to determine if an adjustment (such as a probability-weighted figure) is warranted; document the reasoning either way.
- Get written legal or professional advice close to the balance sheet date for any material claim — auditors and lenders will ask for it, and verbal assurances are not sufficient evidence.
- Review the tax treatment carefully: while general provisions are added back, a specific GAAP-compliant provision for allowable revenue costs is often deductible for corporation tax immediately, provided it is estimated with sufficient accuracy and no specific statutory timing restriction applies.
Not sure whether your claim needs a provision or just a disclosure note?
Our team helps SME owners and finance managers apply IAS 37 and FRS 102 correctly to real legal claims, warranty exposures, and disputes — with clear working papers your auditor and your bank will accept.