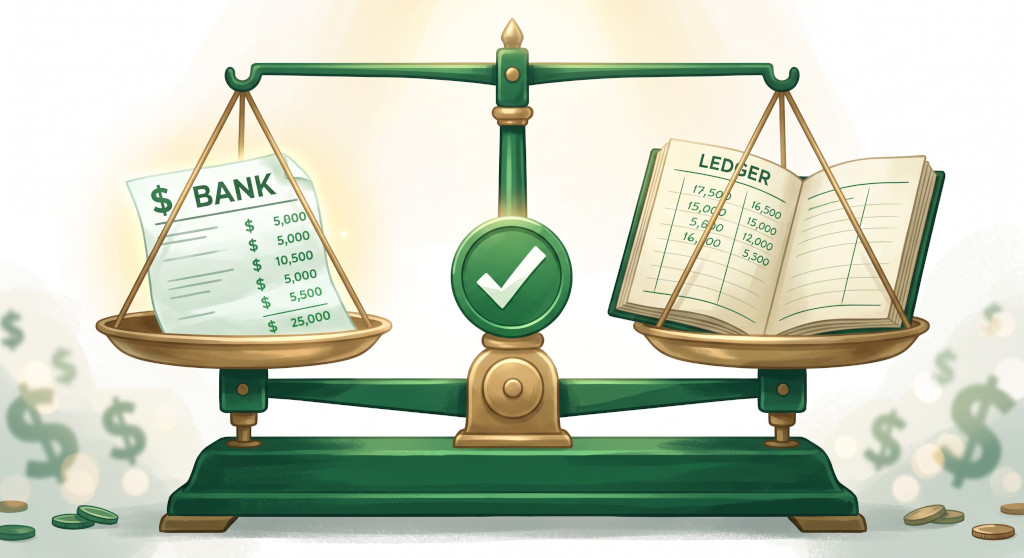
Every month, your bank account tells one version of your finances — and your accounting records tell another. Bank reconciliation is the process of sitting those two versions side by side, finding every difference, explaining every gap, and arriving at a single version of the truth. For a small or medium-sized business, it is one of the most important habits you can build. It catches errors before they compound, spots fraud before it escalates, and gives you confidence that the numbers you are reporting are actually correct.
What Is Bank Reconciliation?
Bank reconciliation is the process of comparing your business’s internal cash records — held in your accounting software or cashbook — against the transactions shown on your bank statement for the same period. The goal is to confirm that both records agree, or to identify and explain why they do not.
The two records will almost never match perfectly at first, and that is entirely normal. Timing differences are the most common reason: a cheque you wrote last week may not have cleared the bank yet, or a payment received on the last day of the month may appear on next month’s statement. These are not errors — they are expected timing gaps that the reconciliation process accounts for.
What the process is really hunting for are genuine discrepancies: a bank charge you forgot to record, a duplicate payment, a customer deposit that your bookkeeper missed, or — in more serious cases — an unauthorised transaction. Bank reconciliation is your first line of defence against all of these.
Why Bank Reconciliation Matters for Your Business
It is tempting to treat bank reconciliation as an administrative chore that accountants insist on for obscure reasons. In practice, it serves several critical functions for any SME owner.
Accurate cash position. Your accounting software only knows what you have told it. If a direct debit went out last Tuesday and nobody entered it, your ledger says you have more cash than you actually do. Reconciliation closes that gap and gives you a reliable cash balance to make decisions from.
Error detection. Transposition errors — entering £1,420 instead of £1,240, for instance — are surprisingly common in manual bookkeeping. They sit invisibly in your records until reconciliation forces a comparison. Finding a £180 discrepancy is far easier in month one than in month twelve when dozens of similar entries have stacked up.
Fraud prevention. Businesses with weak reconciliation controls are more vulnerable to employee fraud. Regular reconciliation creates a paper trail that makes it significantly harder for unauthorised payments to go undetected. The simple fact that someone is checking is itself a deterrent.
Reliable financial reports. Your profit and loss statement, balance sheet, and cash flow statement are only as reliable as the underlying bookkeeping. If your cash figure is wrong, everything downstream from it is wrong too. A clean monthly reconciliation is the foundation on which trustworthy management accounts are built.
Bank reconciliation is not about finding fraud — most of the time, you will find nothing more dramatic than a timing difference or a forgotten bank charge. But it is the only process that guarantees you would find fraud if it were there.
How to Complete a Bank Reconciliation: Step by Step
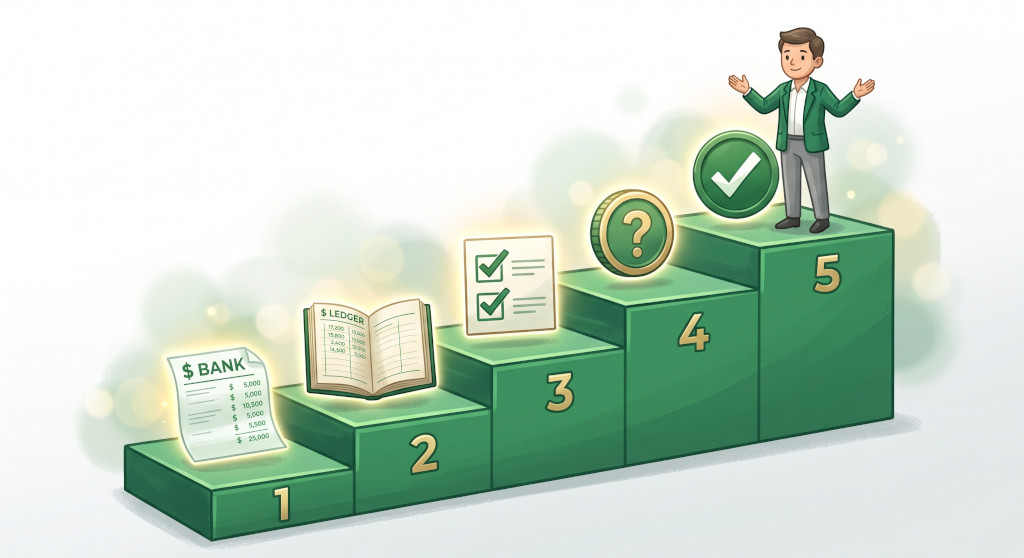
The mechanics of bank reconciliation are the same whether you use accounting software or a spreadsheet. Here is the process laid out clearly, with a worked example.
Step 1: Obtain your bank statement. Log into your online banking and download or print your statement for the period you are reconciling — typically one calendar month.
Step 2: Check your opening balance. Confirm that the closing balance from your previous reconciliation matches the opening balance on this month’s statement. If they do not match, you have an unresolved issue from a prior period that needs to be fixed before you proceed.
Step 3: Match each bank transaction to your records. Go through every item on the bank statement and tick it off against a corresponding entry in your accounting records. Most accounting software does this semi-automatically. In a spreadsheet, work line by line.
Step 4: Identify unmatched items. Anything remaining unticked falls into one of two categories: a timing difference (expected) or a genuine discrepancy (needs action). List them separately.
Step 5: Produce the reconciliation statement. Calculate your adjusted balances and confirm they agree.
Worked Example
Consider a business with the following position at 31 July 2026:
| Item | Amount |
|---|---|
| Bank statement closing balance (31 July) | £18,450 |
| Add: Deposit in transit (received 31 July, not yet on statement) | +£2,100 |
| Less: Outstanding cheque (written 28 July, not yet cleared) | –£850 |
| Adjusted bank balance | £19,700 |
| Cash book balance (per accounting records, 31 July) | £19,950 |
| Less: Bank charge not yet recorded in cash book | –£250 |
| Adjusted cash book balance | £19,700 |
| Difference | £0 ✓ |
The two adjusted balances agree at £19,700. The reconciliation is complete. The business owner now knows they need to post the £250 bank charge to their accounting records, and that the £850 cheque will clear in August.
Common Differences You Will Find — and How to Handle Them
Most reconciling items fall into predictable categories. Knowing what to expect makes the process faster and less stressful.
Deposits in transit. Cash or cheques received and recorded in your books, but not yet showing on the bank statement because the bank has not processed them yet. These are perfectly normal. They will appear on next month’s statement and can be matched then.
Outstanding cheques. Cheques or BACS payments you have recorded in your books, but which the recipient has not yet cashed or the bank has not yet cleared. Again, normal. Keep a running list; if a cheque is outstanding for more than 60–90 days, it is worth investigating whether it was lost.
Bank charges and interest. Banks deduct fees and sometimes credit interest directly. Unless your accounting software imports the bank feed automatically, these are easy to miss. Always check the statement for charges you have not yet entered.
Direct debits and standing orders. Regular automated payments can slip through unrecorded, especially for quarterly or annual subscriptions. Reconciliation is the catch-all.
Errors. If a difference remains after accounting for all timing items, you have a genuine error somewhere — either in your records or, occasionally, at the bank. Investigate the remaining difference systematically: sort by amount, look for entries that are exactly twice the discrepancy (a common sign of a double-entry error), and check recent journal entries.
Fraudulent transactions. In the unlikely event of an unauthorised transaction appearing on your bank statement, reconciliation is the process that surfaces it. Contact your bank immediately and document everything.
How Often Should You Reconcile — and What Tools Help?
Monthly reconciliation is the minimum for any active business. If you process high volumes of transactions — dozens or hundreds per day — weekly or even daily reconciliation is worth considering. The more frequently you reconcile, the shorter each session is and the easier it is to track down discrepancies while the details are still fresh.
Most cloud accounting platforms — Xero, QuickBooks, MYOB, Zoho Books — include bank feed integration that imports transactions directly from your bank, dramatically reducing the manual matching work. Instead of checking every item by hand, you are reviewing suggested matches and confirming them. This can reduce a monthly reconciliation from a two-hour task to a fifteen-minute one.
Even with a bank feed, a human review is still essential. Automated matching is very good, but it cannot flag a bank charge that was coded to the wrong expense category, or spot a payment that looks routine but is not. The reconciliation is not complete until a person has reviewed the output and signed it off.
Keeping good records is closely tied to reconciliation discipline. If you are not sure how your accounts are structured, it helps to start with a solid foundation — a well-organised chart of accounts for your SME makes it much easier to code transactions correctly and spot mismatches quickly.
Key Takeaways
- Bank reconciliation compares your internal cash records against your bank statement to confirm they agree — or to explain why they do not.
- Timing differences (deposits in transit, outstanding cheques) are normal and expected; genuine errors and missing entries require action.
- A clean reconciliation gives you an accurate cash balance, reliable financial reports, and protection against both errors and fraud.
- The five steps are: obtain the bank statement, check the opening balance, match transactions, identify unmatched items, and produce a reconciliation statement.
- Monthly is the minimum frequency; businesses with high transaction volumes should reconcile weekly or daily.
- Cloud accounting software with bank feed integration makes reconciliation significantly faster, but human review is still essential.
- Any unexplained difference at the end of the reconciliation must be investigated and resolved before the books are closed for the period.
Related Reading
- Double-Entry Bookkeeping Explained: How Journal Entries Keep Your Accounts in Balance
- What Is a Trial Balance? A Clear Guide for Small Business Owners
- Accruals and Prepayments Explained: The Accounting Entries Every SME Owner Needs to Understand
- Understanding the Cash Flow Statement: Your Business’s Financial Pulse